ALTERNATIVE INVESTMENT FUNDS
Accrue
Alternative Investment Funds (AIF) in India
Access start-ups & private equity. Hedged strategies. Private credit. Real estate & infrastructure funds. Accrue Finvisor LLP, an AMFI-registered Mutual Fund Distributor (ARN-162637), distributes AIFs.
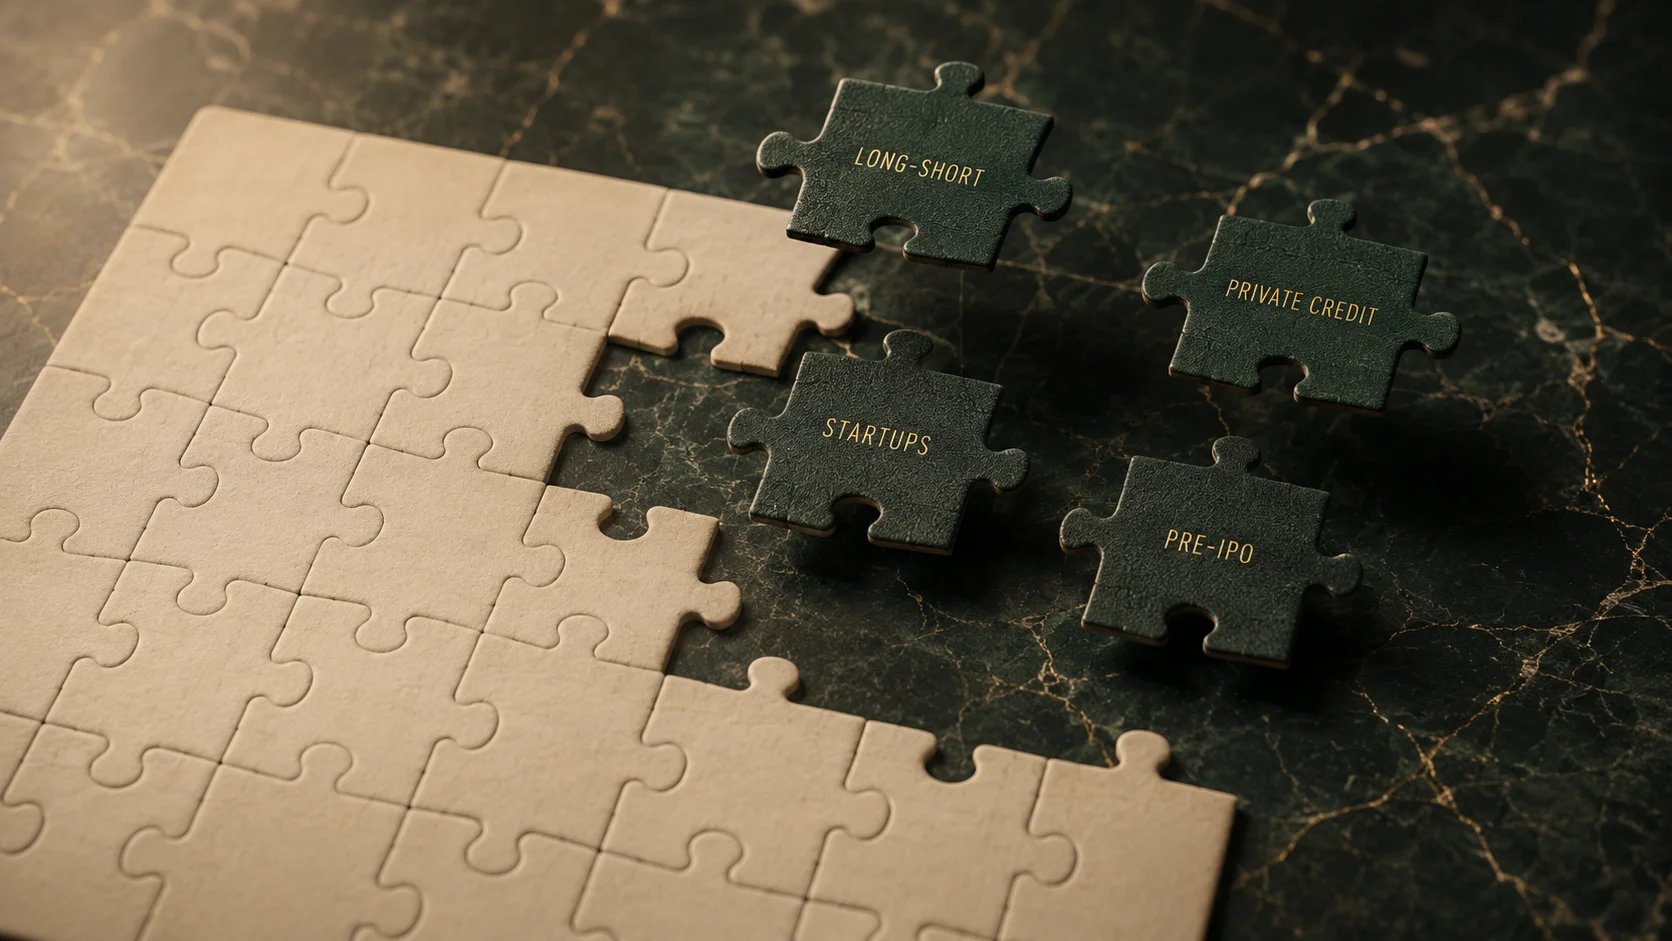
Through AIFs, you can access…
01Startups. SMEs. Growth companies. Pre-IPO equity.
- ◆ India is the world’s 3rd largest startup ecosystem. AIFs let you invest in these companies before they go public.
- ◆ Own equity across every private-market stage — angel, seed, Series A–D, growth capital, SME expansion, and pre-IPO rounds.
02Long-short strategies.
- ◆ These funds buy stocks they expect to rise and short stocks they expect to fall — so they can make money in both directions. Some can hedge up to 100% of the portfolio.
03Private credit. Real estate. Infrastructure.
- ◆ Lend directly to businesses at fixed terms and high yields — returns come from contracts, not stock market movements.
- ◆ Invest in real estate and infrastructure projects — without buying property yourself.
Three categories. Different rules. Different roles.
SEBI classifies AIFs into three categories. The standard minimum investment is ₹1 crore per investor. Angel funds (Category I) have no minimum investment for accredited investors. Who counts as an accredited investor is defined in the comparison below.
CATEGORY I
Category I — Government-incentivised
Invests in startups, early-stage ventures, SMEs, infrastructure, and social enterprises. No leverage beyond short-term borrowing within set limits. Close-ended. Minimum tenure: three years. Includes venture capital funds, angel funds, SME funds, and infrastructure funds.
CATEGORY II
Category II — Standard alternatives
Private equity, private credit, real estate, distressed assets, and fund of funds. No leverage beyond short-term borrowing within set limits. Close-ended. Minimum tenure: three years. The largest segment — approximately 74% of total AIF commitments (Source: SEBI AIF data).
CATEGORY III
Category III — Complex strategies
Long-short equity, PIPE funds, hedge funds, and multi-strategy approaches. Can employ leverage up to 2x NAV. May be open-ended or close-ended. Category III recorded 43.3% year-on-year growth in commitments (Source: SEBI AIF data). Long-short strategies are also offered inside a mutual fund wrapper as Specialized Investment Funds →
Category I, II and III side by side.
Wording follows the SEBI (Alternative Investment Funds) Regulations, 2012, as amended up to 14 July 2026. Each cell names the rule it comes from.
| What is compared | Category I | Category II | Category III |
|---|---|---|---|
| Strategy types the regulation names | Funds that invest in start-up or early-stage ventures, social ventures, SMEs, infrastructure, or other sectors or areas the government or regulators consider socially or economically desirable. Named types: venture capital funds, SME funds, angel funds, social impact funds, infrastructure funds, special situation funds.Reg 3(4)(a) | Funds that fall in neither Category I nor Category III and do not use leverage or borrowing beyond what the regulations permit. The regulation names private equity funds and debt funds as examples, where no specific incentives or concessions are given by the government or any other regulator.Reg 3(4)(b) | Funds that employ diverse or complex trading strategies and may use leverage, including through listed or unlisted derivatives. The regulation names hedge funds, funds that trade to make short-term returns, and other open-ended funds with no specific incentives or concessions.Reg 3(4)(c) |
| What it may invest in | Investee companies, venture capital undertakings, special purpose vehicles, limited liability partnerships, units of other Category I funds of the same sub-category, or units of Category II funds as that regulation specifies.Reg 16(1)(a) | Investee companies, or units of Category I or other Category II funds, as disclosed in the placement memorandum. Primarily unlisted securities and/or listed debt securities (including securitised debt instruments) rated ‘A’ or below by a credit rating agency registered with SEBI, directly or through other AIFs, in the manner SEBI specifies.Reg 17(a) | Securities of listed or unlisted investee companies, derivatives, units of other AIFs, or complex or structured products.Reg 18(a) |
| Borrowing and leverage | No borrowing or leverage, except borrowing for temporary funding and day-to-day operational needs: not more than 30 days, on not more than 4 occasions in a year, and not more than 10% of investable funds, within conditions SEBI sets.Reg 16(1)(c) | No borrowing or leverage, except borrowing for temporary funding and day-to-day operational needs: not more than 30 days, on not more than 4 occasions in a year, and not more than 10% of investable funds, within conditions SEBI sets.Reg 17(c) | May use leverage or borrow with the investors’ consent, within a maximum limit SEBI specifies (note 1). The fund must report its overall leverage and the main source of it to investors and to SEBI.Reg 18(c) |
| Tenure | Close-ended. Minimum tenure three years.Reg 13(1) and (2) | Close-ended. Minimum tenure three years.Reg 13(1) and (2) | A scheme may be open-ended or close-ended.Reg 13(3) |
| Minimum investment per investor | ₹1 crore. The ₹1 crore clause does not apply to an accredited investor (note 3), and the figure is ₹25 lakh for employees or directors of the fund or its manager. Angel funds: “No minimum value of investment shall be applicable for investment in an angel fund by an angel investor.” Special situation funds: note 2. Social impact funds that invest only in securities of not-for-profit organisations registered or listed on a social stock exchange: ₹1,000 for an individual investor.Reg 10(c); Reg 19D(2) | ₹1 crore. The ₹1 crore clause does not apply to an accredited investor (note 3), and the figure is ₹25 lakh for employees or directors of the fund or its manager.Reg 10(c) | ₹1 crore. The ₹1 crore clause does not apply to an accredited investor (note 3), and the figure is ₹25 lakh for employees or directors of the fund or its manager.Reg 10(c) |
- Category III leverage limit. SEBI Master Circular for AIFs, para 7.2.3: “The leverage of a Category III AIF shall not exceed 2 times of the NAV of the fund.”Master Circular for AIFs, para 7.2.3
- Special situation funds are a Category I sub-category with their own minimum. Master Circular for AIFs, para 9.2: “SSF shall accept an investment of value not less than INR 10 crore from an investor. In case of an accredited investor, the SSF shall accept an investment of value not less than INR 5 crore.”Master Circular for AIFs, para 9.2
- Accredited investors are defined in the note under the AIF vs PMS vs SIF comparison below.
Last reviewed
The AIF industry is ₹15.7 lakh crore.
Source: Cafemutual, AIF commitments data (Dec 2025)
FOR INVESTORS EVALUATING AIFS
Start an AIF conversation with Accrue.
Share a few details. We respond to set up an initial conversation — typically within 2 working days. No obligation.
What to understand before committing ₹1 crore for 3+ years.
Lock-in and liquidity
Category I and Category II AIFs are close-ended with a minimum tenure of three years. Each fund sets its own tenure in its placement memorandum, and the tenure can be extended by up to two years (up to five years for an Accredited Investors only fund) with the approval of two-thirds of unit holders by value. Category III may be open-ended with periodic redemption windows. There is no daily NAV and no established secondary market. Capital committed is capital locked.
J-curve effect
In PE and VC AIFs, returns are typically negative in the early years as fees are charged while investments have not yet matured. This is structural, not a sign of failure.
Vintage risk
The year an AIF launches materially affects returns. Capital deployed at the top of a cycle faces different exit conditions than capital deployed during a correction.
Performance dispersion
The gap between the best and worst AIF in the same category is far wider than in mutual funds. Manager selection is the dominant driver of returns.
AIF vs PMS vs SIF.
Regulator, structure, minimum investment and who may invest, in the words of each rulebook.
| What is compared | AIF | PMS | SIF |
|---|---|---|---|
| Regulator and rulebook | Regulator: SEBI. Rulebook: SEBI (Alternative Investment Funds) Regulations, 2012.AIF Regulations, title | Regulator: SEBI. Rulebook: SEBI (Portfolio Managers) Regulations, 2020.PMS Regulations, title | Regulator: SEBI. Rulebook: SEBI (Mutual Funds) Regulations, 2026, Chapter IX (Specialized Investment Fund).MF Regulations 2026, Chapter IX |
| What it is | A privately pooled investment vehicle that collects funds from investors, Indian or foreign, to invest under a defined investment policy. It is set up in India as a trust, company, limited liability partnership or body corporate. It raises funds by private placement only.AIF Regs, reg 2(1)(b); reg 10(g) | A body corporate that, under a contract with a client, manages a portfolio of securities, goods or funds for the client. A discretionary portfolio manager manages each client’s funds “individually and independently”, “in a manner which does not partake character of a Mutual Fund”. Each client’s securities are held in separate accounts.PMS Regs, reg 2(1)(o); reg 23(1); reg 23(4) | A mutual fund. It offers “investment strategies”, each open-ended, close-ended or interval, with the subscription and redemption frequency disclosed in the offer document.MF Regs 2026, reg 2(1)(ww); reg 50(2) |
| Minimum investment | General minimum ₹1 crore. The regulation says an AIF “shall not accept from an investor, an investment of value less than one crore rupees”. That clause does not apply to an accredited investor (note 2), and the figure is ₹25 lakh for employees or directors of the fund or its manager. Angel funds: “No minimum value of investment shall be applicable for investment in an angel fund by an angel investor.” Social impact funds that invest only in securities of not-for-profit organisations registered or listed on a social stock exchange: ₹1,000 for an individual investor.AIF Regs, reg 10(c); reg 19D(2) | ₹50 lakh. The regulation says a portfolio manager “shall not accept from the client, funds or securities worth less than fifty lakh rupees”. For an accredited investor, “subject to appropriate disclosures in the disclosure document and the terms agreed between the client and the portfolio manager, the requirement of minimum investment amount per client shall not apply” (note 2). The minimum applies to new clients and fresh investments by existing clients. The minimum does not apply to a Co-investment Portfolio Manager.PMS Regs, reg 23(2); reg 23(2), co-investment proviso | ₹10 lakh. The regulation says a SIF “shall not accept an investment amount of less than ten lakh rupees from any investor except an accredited investor, across all its investment strategies” (notes 1 and 2). The Master Circular adds that the threshold does not apply to mandatory investments made by AMCs for designated employees.MF Regs 2026, reg 49(1); Master Circular, para 21.4.1 |
| Who may invest | The regulation says an AIF may raise funds from “any investor whether Indian, foreign or non-resident Indians”. Up to 1,000 investors in a scheme, not counting accredited investors. An angel fund raises funds only from accredited investors; its key management personnel may also invest.AIF Regs, reg 10(a); reg 10(f); reg 19D(1) | A client who enters a portfolio management contract with the portfolio manager. Foreign portfolio investors may also use a portfolio manager.PMS Regs, reg 2(1)(o); reg 25 | The only investor-level condition in Chapter IX is the ₹10 lakh minimum, which applies to “any investor” except an accredited investor.MF Regs 2026, reg 49(1) |
- SIF minimum, measured across strategies. Master Circular for Mutual Funds, para 21.4.1: “an aggregate investment by an investor across all investment strategies offered by the SIF, at the PAN level, is not less than INR 10 lakh”.Master Circular for Mutual Funds, 20 Mar 2026, para 21.4.1
- Accredited investor: a person granted a certificate of accreditation by an accreditation agency. For an individual, Hindu undivided family, family trust or sole proprietorship: annual income of at least ₹2 crore; or net worth of at least ₹7.5 crore, of which at least ₹3.75 crore is in financial assets; or annual income of at least ₹1 crore and net worth of at least ₹5 crore, of which at least ₹2.5 crore is in financial assets. For a body corporate or a trust other than a family trust: net worth of at least ₹50 crore. For a partnership firm: each partner meets the criteria. Certain institutions are deemed accredited investors and need no certificate. The SIF regulations (reg 2(1)(b)) give the term the same meaning; the PMS regulations (reg 2(1)(ab)) refer to criteria set by SEBI and a certificate from an accreditation agency.AIF Regs, reg 2(1)(ab)
For information only. This compares rules; it is not advice or an offer, and it does not rank the three. All three carry investment risk, including loss of capital.
Investments in Specialized Investment Fund involves relatively higher risk including potential loss of capital, liquidity risk and market volatility. Please read all investment strategy related documents carefully before making the investment decision.
Sources
- SEBI (Alternative Investment Funds) Regulations, 2012, as amended up to 14 July 2026. SEBI page · SEBI text
- SEBI Master Circular for Alternative Investment Funds, issued 3 June 2026, last updated 7 September 2026. SEBI text
- SEBI (Portfolio Managers) Regulations, 2020, as amended up to 3 September 2025. SEBI text
- SEBI (Mutual Funds) Regulations, 2026, as amended up to 7 July 2026. SEBI text
- SEBI Master Circular for Mutual Funds, 20 March 2026. SEBI text
Last reviewed
AIF access for NRI investors.
FEMA permits NRI investment across all three AIF categories, through NRE or NRO accounts.
BANKING ROUTES
NRE vs NRO accounts
NRE accounts offer full repatriation of principal and returns. NRO accounts carry annual repatriation limits. The choice affects post-investment flexibility.
GIFT CITY
GIFT City AIFs
GIFT IFSC offers USD-denominated AIF structures with tax benefits for non-resident investors — a distinct route for dollar-denominated India exposure.
For a broader overview of cross-border investment considerations for NRI families, see Accrue’s dedicated NRI page →
Frequently asked questions.
Can I invest in AIFs with ₹25 lakh?
The standard SEBI-mandated minimum is ₹1 crore per investor. Angel funds under Category I have no minimum investment for accredited investors. For most strategies — private credit, long-short, PE — the standard minimum is ₹1 crore. In every category, the ₹1 crore clause does not apply to an accredited investor (reg 10(c)).
How liquid are AIFs compared to PMS or mutual funds?
Category I and II AIFs are close-ended with a minimum tenure of three years, with no daily NAV and no established secondary market. Category III open-ended funds offer periodic redemption windows. PMS withdrawal terms are set in each client’s agreement. Most open-ended mutual fund schemes offer daily redemption. AIFs are structurally illiquid — capital committed is capital locked.
What is the real all-in cost of AIF investing?
Management fee (1–2.5% p.a.), performance fee (15–20% of profits above an 8–10% hurdle), plus GST, fund expenses, and legal costs. High-water mark provisions and clawback mechanisms protect against over-earning by the manager.
Should I choose AIF or PMS?
Different instruments for different roles. PMS provides segregated accounts with direct stock ownership — withdrawal terms are set in each client’s agreement. AIFs are pooled vehicles accessing private markets, unlisted securities, and complex strategies — with multi-year lock-ins. Standard minimums: PMS ₹50 lakh; AIF ₹1 crore. Neither minimum applies to an accredited investor (AIF reg 10(c); PMS reg 23(2), subject to disclosures). The choice depends on the role the allocation plays in the overall portfolio.
Can NRIs invest in AIFs? What about US-based NRIs?
FEMA permits NRI investment across all three categories through NRE or NRO accounts. US NRIs face additional complexity: PFIC classification risk, FATCA compliance, and Form 8621 filing. Many AIF managers are cautious about accepting US NRI investors. GIFT City IFSCA offers USD-denominated AIF structures with tax benefits for non-residents. Cross-border tax advice is essential.
How does Accrue evaluate AIFs?
Accrue evaluates across four dimensions: strategy consistency, manager track record and team stability, cost structure and fee waterfalls, and vintage and cycle positioning. Accrue is a distributor — it evaluates and distributes AIFs from SEBI-registered managers.
What risks should I understand before committing?
A minimum tenure of three years for Category I and II funds, J-curve in PE/VC funds (negative early returns as fees are charged before investments mature), limited liquidity, wide performance dispersion between top and bottom quartile managers, complex tax treatment (especially Category III), vintage risk (entry timing matters), and no secondary market infrastructure for most funds.
Answers are for general information and educational purposes only. They do not constitute personalised investment advice or an offer to subscribe to any AIF scheme. AIF investments are subject to market risks. Past performance is not indicative of future returns. Consult a SEBI-registered investment adviser for personalised guidance.
Start a conversation
Share how Accrue can help.
Choose what is on your mind, or write your own. We respond within 2 working days.